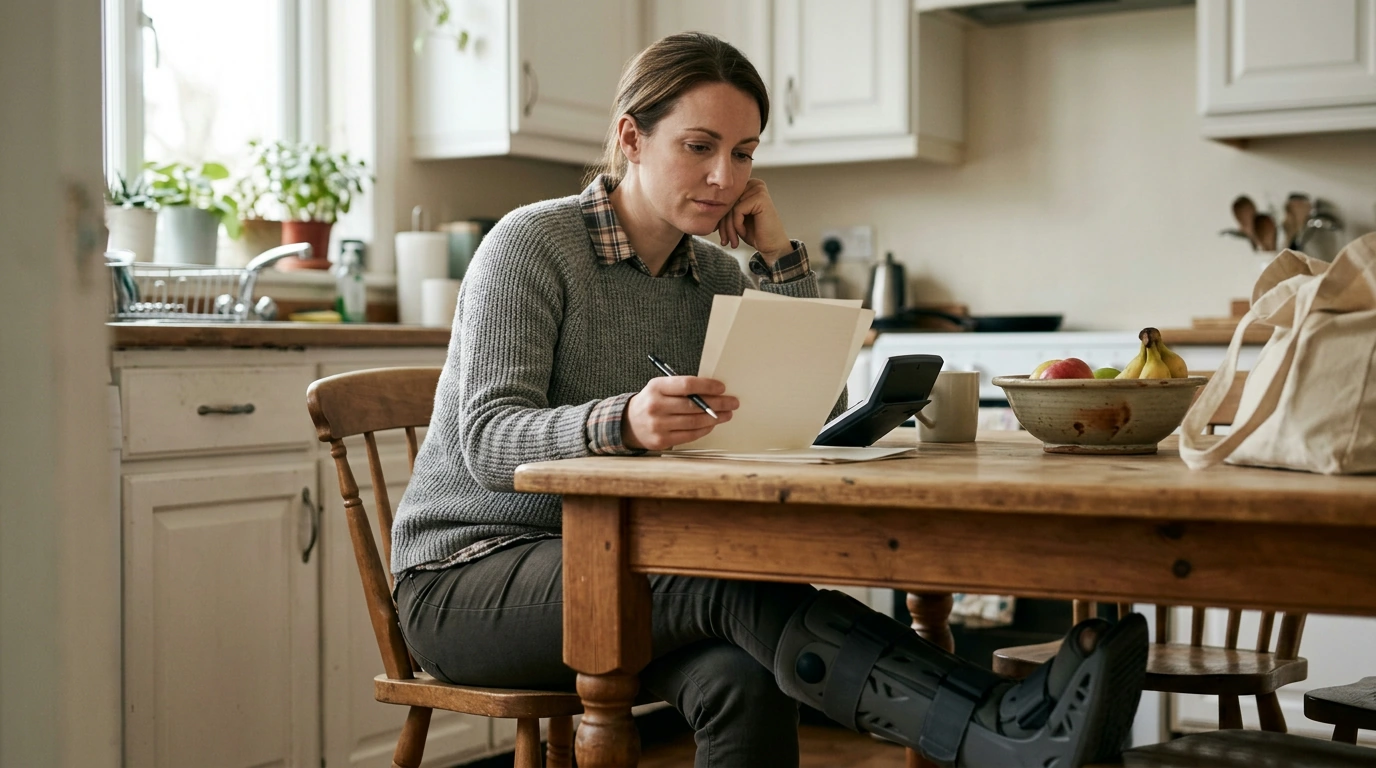
An illness or injury can interrupt your income while rent, groceries, and other bills continue. Disability insurance is one way to plan for that possibility, although coverage and benefits depend on the policy you choose and your circumstances.
Our guide is a starting point for exploring income protection. Before you decide whether you need coverage, consider how long your household could manage without your usual paycheck and what benefits you already have.
A missed paycheck can affect more than discretionary spending. Housing, food, utilities, transportation, and debt payments may still be due even when you cannot work. You might turn to savings to bridge the gap, but a lengthy interruption could make it harder to preserve an emergency fund or meet other financial goals.
Health insurance and disability insurance address different risks. Health insurance generally helps cover eligible medical costs. Disability insurance may replace part of your eligible income if a qualifying disability prevents you from working under the policy’s terms. Having one does not necessarily provide the protection offered by the other.
Benefits are not automatic. A claim must meet the policy’s definition of disability and other requirements, and exclusions or limits may apply. Understanding those details before you need coverage can help you plan more realistically.
When a covered illness or injury prevents you from working, you can submit a claim to the insurer or plan administrator. The claim is assessed against the policy’s requirements. If it is approved, eligible payments may begin after a waiting period and continue for a specified benefit period, subject to the plan’s terms.
Short-term coverage is generally intended for a shorter interruption, while long-term coverage can provide benefits for a longer period. However, waiting periods, payment durations, and definitions vary. Do not assume that every short-term or long-term plan works the same way.
| Feature | What to check | Why it matters |
|---|---|---|
| Benefit amount | How much income the policy may replace | Helps assess whether essential expenses could be covered |
| Waiting period | How long before eligible benefits begin | Shows how much savings may be needed during the gap |
| Benefit period | How long eligible payments may continue | Helps assess protection during an extended disability |
| Definition of disability | How the policy defines inability to work | Affects when a claim may qualify |
| Exclusions and offsets | Limits, exclusions, and other benefits that may reduce payments | Helps clarify potential gaps in coverage |
As you compare options, ask whether the policy measures your inability to perform your own occupation or applies another standard. Also ask how other income or benefits might affect a payment. These distinctions can matter as much as the advertised benefit amount.
You may have access to disability coverage through an employer, or you may be able to purchase an individual policy. Workplace plans and individual policies can differ in cost, eligibility, benefit amounts, and other terms. Employer coverage may also change if you leave your job, so ask what happens to your benefits when employment ends.
Start by reviewing your workplace benefits documents. Look for the coverage amount, waiting period, and conditions for receiving payments before deciding whether additional protection is appropriate. Your benefits department can help you find the relevant plan information.
Public disability programs have their own eligibility rules and may not replace private coverage. For example, you can review the Social Security Administration’s disability benefits information to learn about its requirements. The U.S. Department of Labor’s disability benefits resources also provide a starting point for understanding available programs.
List your essential monthly expenses, including housing, food, utilities, insurance, transportation, and minimum debt payments. Then compare that total with your accessible savings and any existing benefits. Consider both the immediate gap before payments could start and the possibility of a longer absence from work.
Next, compare premiums alongside benefit amounts, definitions of disability, waiting periods, benefit durations, exclusions, and offsets. A lower cost may be attractive, but the details determine when and how much a policy could pay. A licensed insurance professional can help you assess the tradeoffs for your income, household, and existing coverage.
For a resource to support your exploration of income protection, our Why Disability Insurance Is a Must-Have: The Essential Guide for Financial Security is listed at $10.99.
Planning ahead can also apply to other parts of your budget. If you are organizing future travel, our Smart Routes: Plan the Perfect Road Trip – How to Plan a Road Trip Route with Stops Guide is a separate resource for route planning.
For your next step on income protection, gather your existing benefits documents and write down the questions you want to bring to a licensed insurance professional. Our team encourages you to compare the answers with your essential expenses and available savings before making a decision.
Health insurance generally helps pay eligible medical expenses, while disability insurance may replace part of your eligible income if you meet the policy’s requirements.
It depends on your expenses and savings as well as the plan’s benefit amount, waiting period, duration, and exclusions. Review your plan documents to identify potential gaps.
Benefit periods vary by policy and coverage type. Check your plan’s terms for how long eligible payments may continue.



Leave a comment