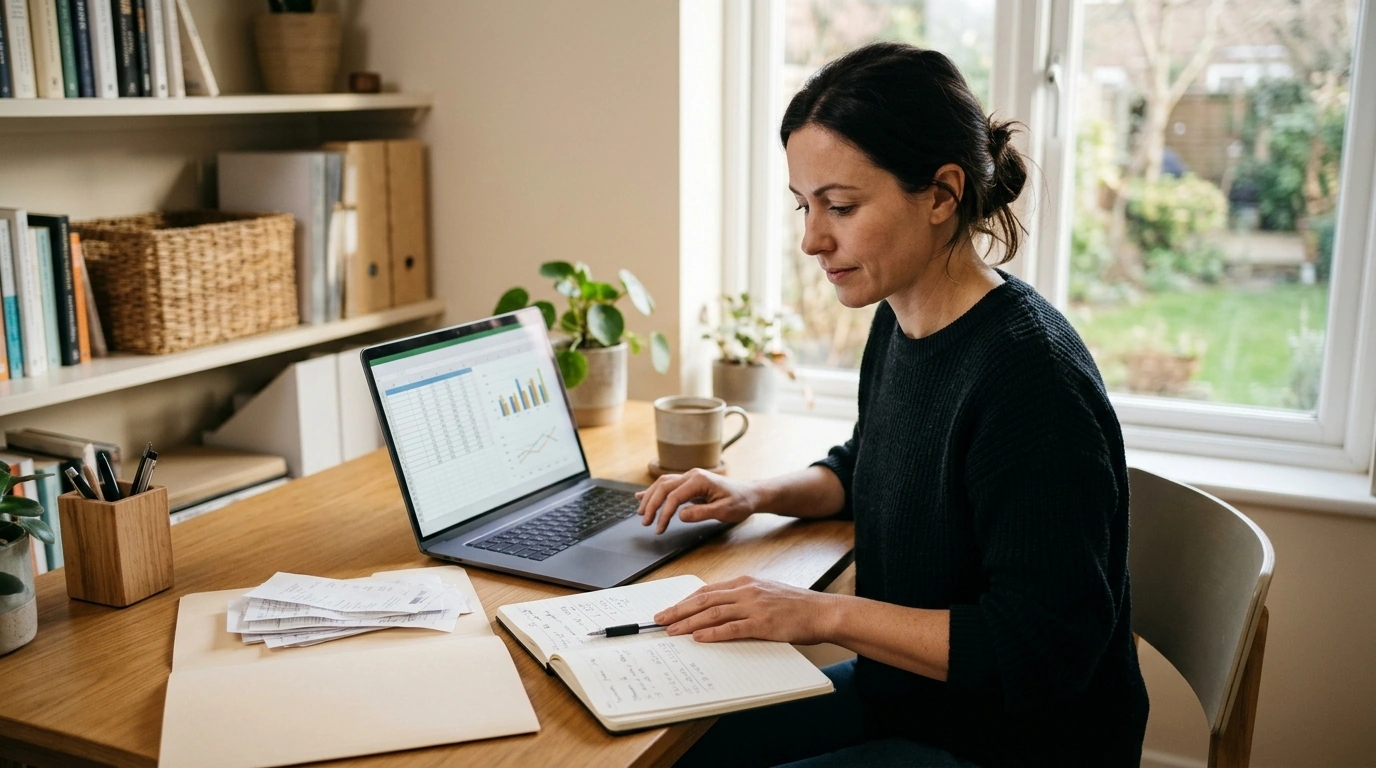
When you work for yourself, a strong sales month does not automatically tell you what you will owe at tax time. Business expenses, other wages, income tax, and payments you have already made all affect the picture. An AI-assisted calculator can help you turn your records into a working estimate—as long as you know what to enter and what to verify afterward.
Gross business income is the money your business brings in before expenses. Net profit is generally what remains after you subtract eligible, ordinary and necessary business expenses. If clients paid you $50,000 and you had $10,000 in deductible expenses, your starting profit figure would be $40,000—not $50,000. Keep records that support both the income and the deductions rather than relying on a calculator to decide which expenses qualify.
Before you open a calculator, gather your business income and expense totals, any W-2 wages, filing status, prior-year tax information, and federal tax payments or withholding to date. You may also need information about other income, deductions, and credits to estimate your overall federal liability. Self-employment tax and federal income tax are separate calculations: a self-employment tax estimate alone is not your complete tax bill.
For a typical calculation, net earnings from self-employment are generally figured as 92.35% of net profit. Social Security and Medicare tax rules then apply to those earnings. The Social Security portion has an annual wage base, and wages from an employer can affect how much of that base remains available for self-employment earnings. Medicare tax follows different rules; Additional Medicare Tax may apply when income exceeds the applicable threshold.
You may also be able to deduct one-half of your self-employment tax as an adjustment to income. That adjustment can affect your income tax calculation; it does not mean you pay only half the self-employment tax you calculated. Current-year rules and your full circumstances matter, so use this table as a map of the inputs, not as a replacement for Schedule SE.
| Step | What to enter or check | Why it matters |
|---|---|---|
| Business net profit | Income minus eligible business expenses | Provides the starting point for the estimate |
| Net earnings | Apply the generally used 92.35% factor | Establishes the amount generally considered for self-employment tax |
| Other wages | Add W-2 wages when relevant | May affect how much income remains below the Social Security wage base |
| Other tax factors | Review filing status, income tax, credits, and payments | Helps turn one tax estimate into a broader payment plan |
For the applicable rules and forms, consult the IRS self-employment tax guidance. It is especially useful when you have both business earnings and employee wages.
Our team recommends a repeatable routine: enter figures backed by your records, confirm the calculator’s tax year and assumptions, save a dated copy of the result, and compare its method with the applicable IRS instructions. If a tool cannot show how it reached a number, treat that number as a question to investigate, not a figure to copy onto a return.
Scenario testing can help you plan. Try a realistic higher-revenue quarter, or see how a planned deductible business purchase might change an estimate. Keep those projections separate from actual transactions: a hypothetical result is not a filed return or proof that a purchase qualifies for a deduction.
Protect your information, too. You usually do not need to paste a Social Security number, full bank statements, or complete client records into an unfamiliar AI tool to get a rough estimate. Review its privacy practices and share only the totals needed for the calculation.
If you want focused help building that routine, our Mastering Self-Employment Taxes with AI Calculators guide is a companion to your records and current IRS instructions, not a substitute for professional advice. If your self-employment work includes video projects, our AI storyboards checklist can support project planning; keep those project decisions separate from decisions about deductible expenses.
Unlike employee paychecks, self-employment income generally does not arrive with federal tax withheld. That is why you may need to make estimated tax payments during the year. The IRS estimated taxes guidance and current-year Form 1040-ES instructions explain payment rules and due dates. Do not assume every payment deadline falls exactly three months after the last one.
Update your income and expense totals regularly, set aside money as revenue arrives, and rerun your estimate when earnings change substantially. Include withholding and estimated payments already made so you do not plan to pay the same amount twice.
Estimated-payment safe-harbor rules often look to a percentage of either current-year tax or prior-year tax. Eligibility, thresholds, and exceptions can change the answer, so use the current IRS instructions before choosing a payment amount. Your practical next step is simple: gather your records, run an estimate, check it against IRS guidance, and ask a qualified tax professional for help if your circumstances are complex.
No. It can help you organize figures and estimate a result, but use current IRS forms and instructions to determine what belongs on your return.
Generally, the calculation starts with net business profit rather than gross client payments, subject to applicable rules and thresholds.
Review it whenever income or expenses change substantially and before estimated-payment deadlines.


Leave a comment