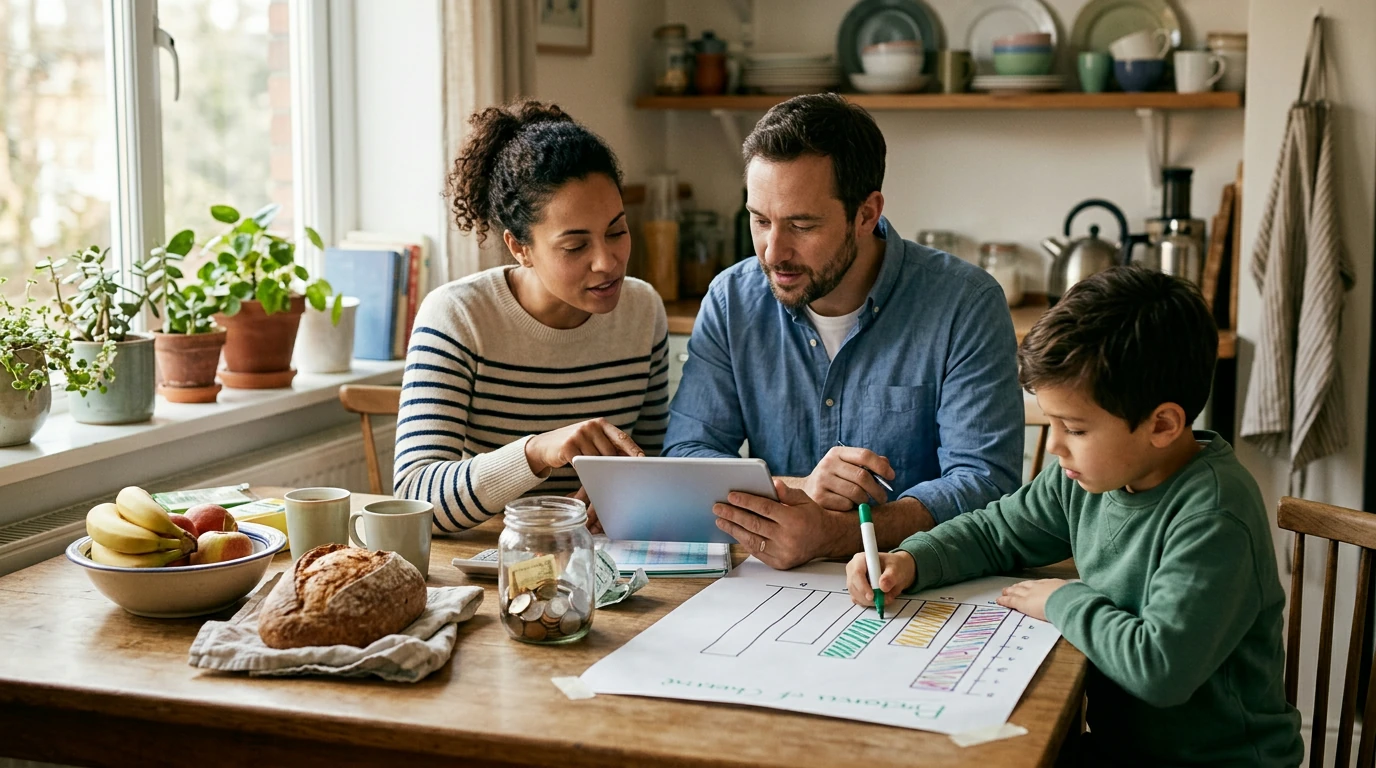
Saving money together works best when the plan fits real family life. A shared budget can make room for everyday needs, surprise expenses, and goals you care about without turning every purchase into a debate. You do not need to settle every financial question in one sitting. Start with a goal, look at what your household actually spends, and choose a date to talk again.
“Save more” is hard to act on. “Set aside $300 for school supplies by August” gives your family something to plan around. Choose one or two goals, give each a target amount, and decide when you will review your progress. The goal might be a holiday fund, a cushion for surprise bills, or money for an experience you want to share.
Invite everyone to suggest ideas, but keep adult financial decisions with the adults. Children can help name a goal or mark progress on a chart without being asked to worry about whether the bills will get paid. Talk about what saving makes possible as well as the choices it requires. If your first target is small enough to reach, completing it can make the next goal feel less distant.
When several goals compete, ask which has a deadline and which would protect the household from a setback. A school expense due next month may need attention before a trip planned for next year. That does not mean the trip disappears; it means you give each goal a place and a realistic turn.
Begin with monthly take-home income, then list regular bills, flexible spending, and expenses that appear only a few times a year. Recent transactions are usually more useful than memory. Look through your account and card activity for recurring charges, grocery spending, and costs that surprised you. If income changes from month to month, base the plan on an amount you can reasonably count on and decide separately what to do with any extra.
Next, distinguish essentials from costs you can adjust. Housing, utilities, transportation, and groceries need room before extras. That does not mean a workable budget must eliminate every treat. A modest amount for meals out or entertainment can make the plan easier to live with. Our aim is a budget you can return to, not one that looks perfect for a week.
| Budget area | What to check together | Possible next step |
|---|---|---|
| Essentials | Housing, groceries, utilities, and transportation | Set aside what you need before planning extras. |
| Flexible spending | Meals out, subscriptions, and entertainment | Choose one change your family can sustain. |
| Occasional costs | Birthdays, school expenses, and repairs | Save a little each month when possible. |
| Shared goals | The target amount and time frame | Agree on a contribution and review date. |
Replace the examples with your own numbers. For an occasional cost, add up what you expect to spend over the year and divide it into manageable monthly amounts. Even if you cannot set aside the full amount yet, naming the expense helps you avoid treating it as a surprise every time it arrives. For more tools to guide your conversation, the Consumer Financial Protection Bureau’s Your Money, Your Goals resources cover budgeting and saving, while FDIC Money Smart offers financial education materials.
Pick a short monthly check-in. Look at what came in, what went out, and whether your planned contribution still fits. Keep the conversation focused: What worked? What changed? What is one adjustment for next month? A calendar reminder can help, but the meeting does not need to be formal. Fifteen minutes at the kitchen table may be enough to keep the plan moving.
Give saved money a clear destination. You might use a dedicated savings account or a labeled category in your budget. Record the amount you add and the new total somewhere you can easily find it. If you share progress with children, a simple visual tracker can show how small contributions add up without sharing financial details they do not need to manage.
Unexpected costs will sometimes interrupt the plan. When that happens, cover the immediate need, then revisit the savings amount or deadline without assigning blame. Saving $10 in a difficult month instead of the usual $40 is still a decision to keep the goal in view. If you need to pause entirely, choose a date to reconsider rather than leaving the plan open-ended.
If you want a focused starting point for the conversation, our Family First, Finances Next digital guide centers on saving money together and planning for family goals. Use it alongside your household’s actual income, expenses, and priorities. No guide can decide what matters most to your family, but a shared place to begin can help you turn a broad intention into a next step.
A family trip is one example of a goal that becomes easier to discuss when you separate the savings target from the planning details. First decide what you can set aside and when you hope to go. Then estimate transportation, lodging, food, and activities before making commitments. If a road trip is your chosen goal, our Smart Routes road trip planning guide can help you organize the route and stops while your budget sets the spending limits.
Start with a brief monthly review. Check sooner if income, bills, or family needs change.
Choose an amount that fits the current month, even if it varies. Revisit the goal and timeline rather than abandoning the plan.



Leave a comment